
Backtest Results
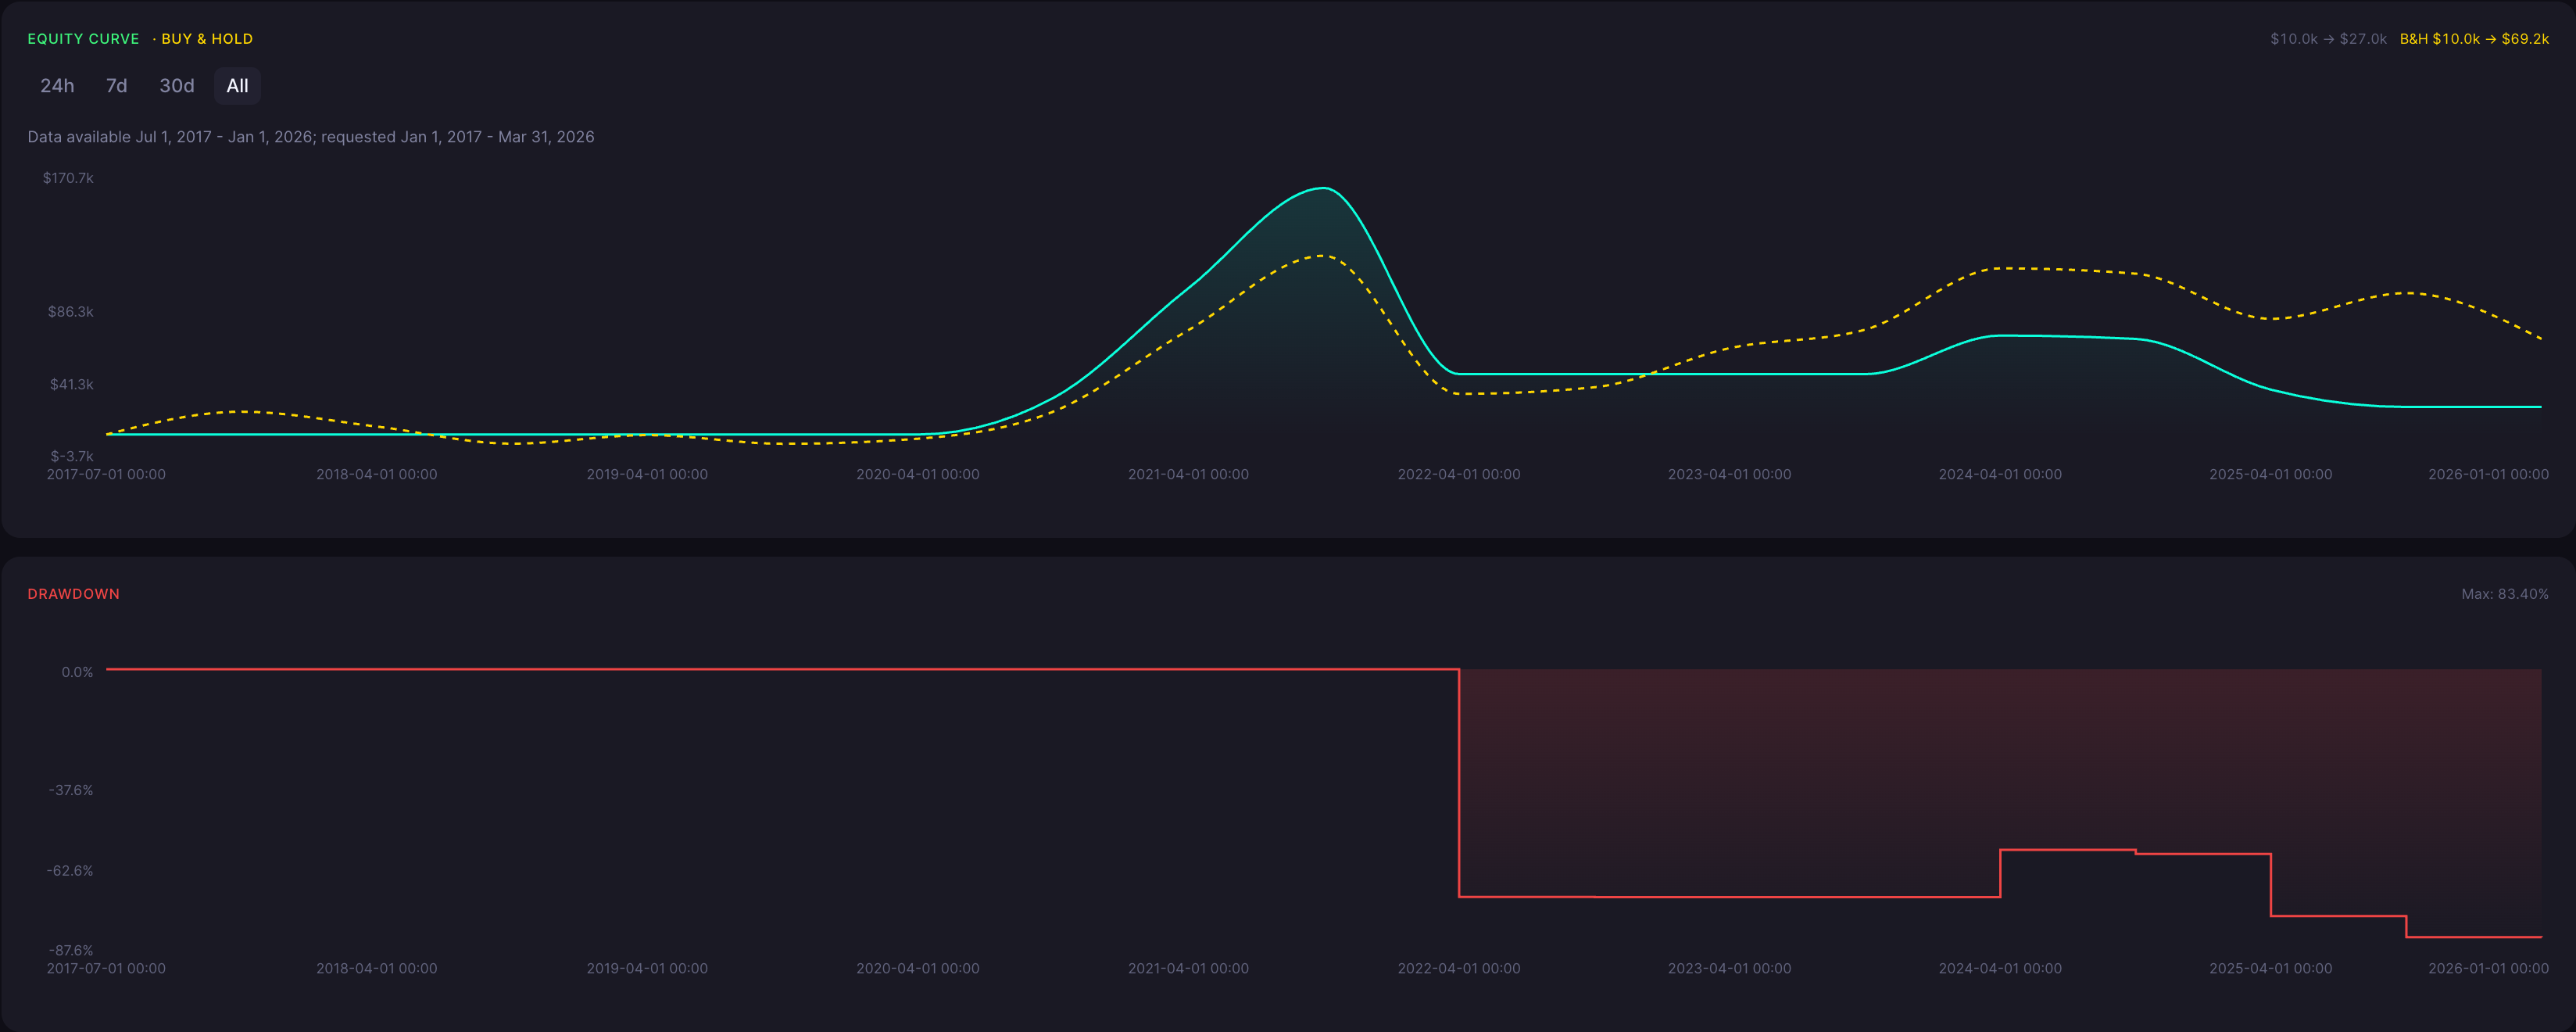
CoinQuant tested this long-only ETH/USDT crossover over 1 Jul 2017 to 1 Jan 2026 using three-month candles. Starting capital of 10,000.00 USDT became 27,022.18 USDT, with a reported return of 170.22%. The figures below show the accompanying drawdown and trading results, rather than just the ending balance.
ROI
170.22%
Win Rate
33.33%
Max DD
83.40%
Sharpe
0.44
Profit Factor
1.84
Total Trades
3
Backtest insights
The return of 170.22% came with a maximum drawdown of 83.40%, meaning the account experienced a substantial decline from an earlier peak. A 33.33% win rate across 3 trades provides little basis for judging repeatability. The positive ending result therefore needs to be considered alongside the size of the losses along the way. Neither the return nor the profit factor of 1.84 establishes that future results would be consistent.

Performance may vary depending on market conditions. During trending periods, the strategy may behave differently compared to ranging markets, impacting both returns and drawdowns.
How the Weighted Moving Average(10) Crossover Strategy Works
What It Is
A weighted moving average combines recent closing prices while giving newer prices more influence. This strategy uses a 10-period average on three-month candles to decide when to hold ETH/USDT, rather than trying to predict a price target.
How Signals Are Generated
Using Close as the indicator source, the strategy enters a long position when Close crosses above the 10-period Weighted Moving Average. It exits when Close crosses below that average. Being above or below alone is not a new crossing.
When It Works Best
Sustained directional trends can give a crossover approach room to follow a move before the next exit. That is a general feature of trend-following rules, not an explanation established by this small set of trades.
When It Performs Poorly
Sideways or rapidly reversing markets can produce entries that soon reverse. Three-month candles also make signals slow to develop, so substantial price changes may occur before an exit. The rules do not prevent losses.
Strengths

Clear crossing conditions make entry and exit decisions understandable.
Recent closing prices receive more weight in the average.
The same rules can be tested across other periods.
Limitations

Very long candles provide few opportunities to assess the rules.
Only 3 trades limit confidence in the win rate.
The maximum drawdown of 83.40% shows substantial historical downside.
Why Use CoinQuant Instead of Manual Trading or Other Platforms
Choosing the right way to test and execute trading strategies is critical. Below is a comparison between CoinQuant, manual trading, and other platforms to highlight key differences in speed, accuracy, and usability.
CoinQuant is designed specifically for traders who want to validate strategies quickly and reliably without coding. Unlike manual trading or traditional platforms, it allows you to test multiple scenarios, analyze performance instantly, and iterate faster using real data.
Frequently asked questions
How does the Weighted Moving Average(10) Crossover strategy perform on ETH/USDT in the 3 Month timeframe?
The performance of the Weighted Moving Average(10) Crossover strategy on ETH/USDT in the 3 Month timeframe depends on market conditions. Based on the backtest results above, it achieved a return of 170.22% with a maximum drawdown of 83.40%. Results may vary depending on volatility and overall market trends.
Is the Weighted Moving Average(10) Crossover strategy reliable for trading ETH/USDT?
The Weighted Moving Average(10) Crossover strategy can be effective when used in the right conditions. For ETH/USDT, it typically performs well in sustained directional trends but may underperform during sideways or rapidly reversing markets. Backtesting helps evaluate its reliability before applying it in live trading.
Why is backtesting important for trading strategies?
Backtesting allows traders to evaluate how a strategy would have performed using historical data. It helps identify strengths, weaknesses, and risk levels before applying the strategy in real markets, reducing the likelihood of unexpected losses.
How can I test the Weighted Moving Average(10) Crossover strategy on CoinQuant?
You can use CoinQuant to build and backtest the Weighted Moving Average(10) Crossover strategy without coding. Simply select your asset, define your strategy rules, and run a backtest to view detailed performance metrics instantly.
What are the best settings for the Weighted Moving Average(10) Crossover strategy on 3 Month?
The best settings for the Weighted Moving Average(10) Crossover strategy depend on the asset and timeframe. Traders often adjust parameters based on volatility and trading style. Using a backtesting platform like CoinQuant allows you to test different configurations and identify what works best.