
Backtest Results
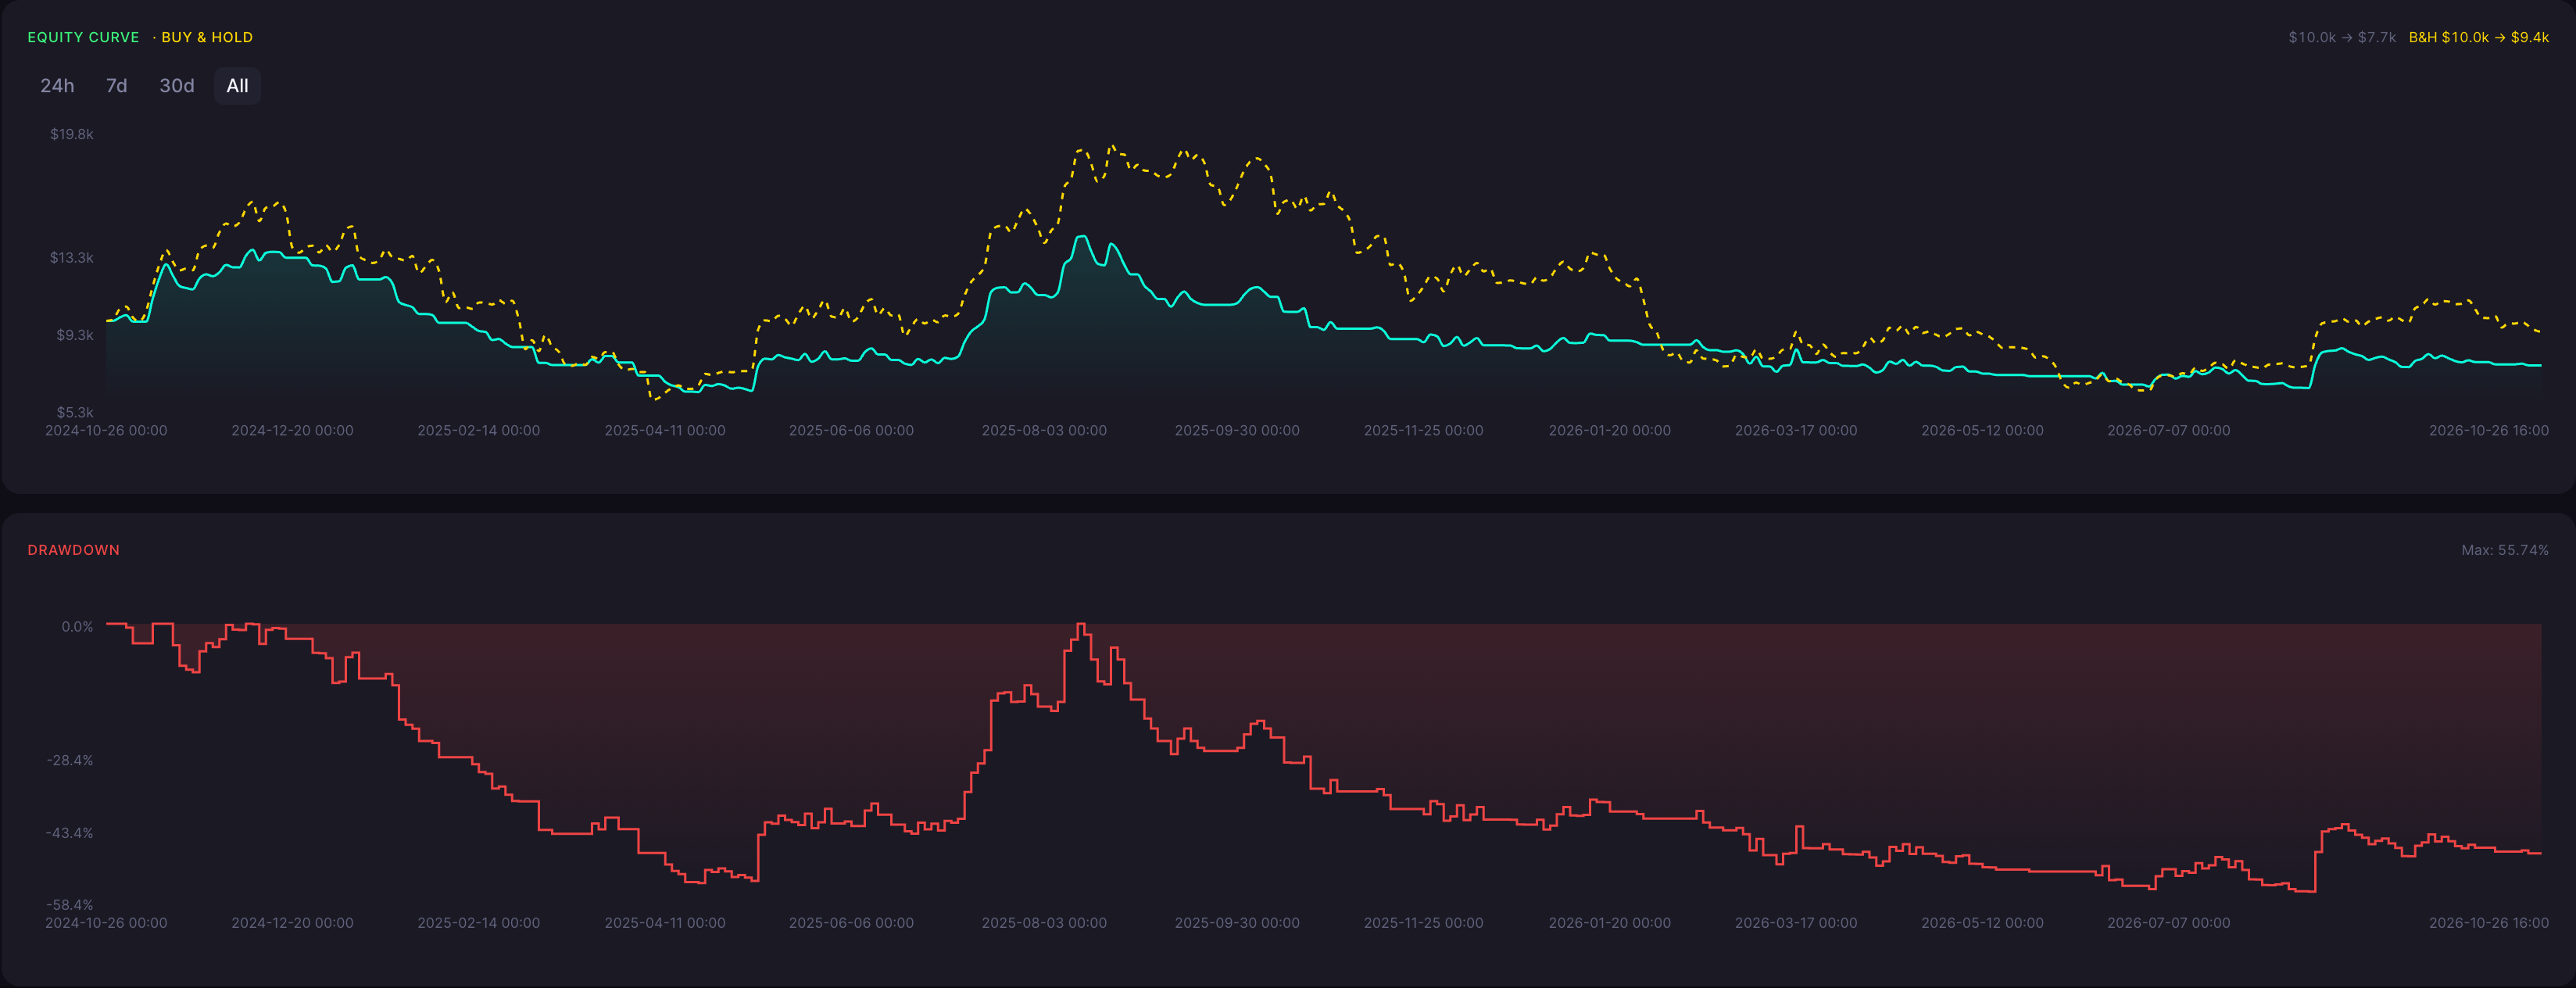
The backtest covered 26 Oct 2024 to 26 Oct 2026. The test dates were not shortened, and no issues were flagged. This does not confirm that the full price history was complete. The strategy started with 10,000.00 USDT and ended with a final balance of 7,705.68 USDT. That is a total return of -22.94% across 153 trades. For reference, a simple buy-and-hold approach over the same test dates ended at 9,427.89.
ROI
-22.94%
Win Rate
22.22%
Max DD
55.74%
Sharpe
-0.06
Profit Factor
0.89
Total Trades
153
Backtest insights
This run finished with a total return of -22.94%, ending below its 10000.0 USDT starting capital. Only 22.22% of the 153 trades were winners. The profit factor of 0.89 indicates that gross losses outweighed gross gains over the test. The Sharpe ratio of -0.06 is slightly below zero. At its deepest point, the account was 55.74% below a prior peak, and the result lists 16 consecutive losses. These figures describe this single run only and do not, on their own, explain why the strategy lost.

Performance may vary depending on market conditions. During trending periods, the strategy may behave differently compared to ranging markets, impacting both returns and drawdowns.
How the RMA Strategy Works
What It Is
RMA here refers to the Running Moving Average. The original request asked for a Running Moving Average with a 10-period length and the Close price as its source. In the saved strategy, the indicator field is named RelativeMovingAverage, with period 10 and price type close. The saved condition descriptions read Running Moving Average. This page does not confirm the exact formula used. It also does not confirm that these two names describe the same calculation.
How Signals Are Generated
The saved rules use two conditions on the 8h timeframe:
Entry: when Close crosses above RelativeMovingAverage (period 10, Close source), the rule is set to enter_long with a market order.
Exit: when Close crosses below RelativeMovingAverage (period 10, Close source), the rule is set to exit_long with a market order.
The strategy is long-only, holds at most one open entry, and sizes each position at 100% of current equity. The saved conditions also include other settings. These include a debounce of 5 bars, a confirmation flag, and generic oscillator and divergence fields. Their effect on this run is not documented here. For that reason, this page does not claim that every crossing produced a trade.
When It Works Best
General theory, not measured in this run: moving average crossover strategies tend to suit markets that move in one direction for an extended time. In that kind of market, price can stay above the average long enough for a long position to capture part of a sustained rise. This backtest did not measure trend strength or market regime, so this section is background only.
When It Performs Poorly
General theory, not measured in this run: moving average crossovers often struggle in sideways or choppy markets. In those markets, price can cross back and forth over the average without following through. This backtest did not measure regime and does not attribute its losses to any specific market condition. Treat this section as general background, not as an explanation of the results above.
Strengths

Simple, rule-based logic: one entry and one exit condition, both based on Close and a single 10-period average.
Long-only design with at most one open entry, which keeps the position structure easy to follow.
Fully specified configuration, with the exact prompt and saved settings listed on this page for review.
Limitations

Single losing run: this historical run lost money, with a total return of -22.94%, a maximum drawdown of 55.74% and a profit factor of 0.89. One run on one asset and timeframe is not enough to judge the strategy in general.
Unknown costs: trading costs are unknown, not zero. Trading costs were not provided for this test. The result lists total fees of 2,753.08, but the fee rates and how fees affected the outcome are not known.
Formula and history uncertainty: the exact formula behind the strategy's moving average is not confirmed. How much early price history the strategy needed before trading, and whether the full price history was complete, are not documented. The reported 2293 bars and 732 performance observations do not prove either one.
Why Use CoinQuant Instead of Manual Trading or Other Platforms
Choosing the right way to test and execute trading strategies is critical. Below is a comparison between CoinQuant, manual trading, and other platforms to highlight key differences in speed, accuracy, and usability.
CoinQuant is designed specifically for traders who want to validate strategies quickly and reliably without coding. Unlike manual trading or traditional platforms, it allows you to test multiple scenarios, analyze performance instantly, and iterate faster using real data.
Frequently asked questions
How does the RMA strategy perform on ETH in the 8 hour timeframe?
The performance of the RMA strategy on ETH in the 8 hour timeframe depends on market conditions. Based on the backtest results above, it achieved a return of -22.94% with a maximum drawdown of 55.74%. Results may vary depending on volatility and overall market trends.
Is the RMA strategy reliable for trading ETH?
The RMA strategy can be effective when used in the right conditions. For ETH, it typically performs well in sustained directional trends (general theory, not measured in this run) but may underperform during choppy or sideways markets (general theory, not measured in this run). Backtesting helps evaluate its reliability before applying it in live trading.
Why is backtesting important for trading strategies?
Backtesting allows traders to evaluate how a strategy would have performed using historical data. It helps identify strengths, weaknesses, and risk levels before applying the strategy in real markets, reducing the likelihood of unexpected losses.
How can I test the RMA strategy on CoinQuant?
You can use CoinQuant to build and backtest the RMA strategy without coding. Simply select your asset, define your strategy rules, and run a backtest to view detailed performance metrics instantly.
What are the best settings for the RMA strategy on 8 hour?
The best settings for the RMA strategy depend on the asset and timeframe. Traders often adjust parameters based on volatility and trading style. Using a backtesting platform like CoinQuant allows you to test different configurations and identify what works best.