
Backtest Results
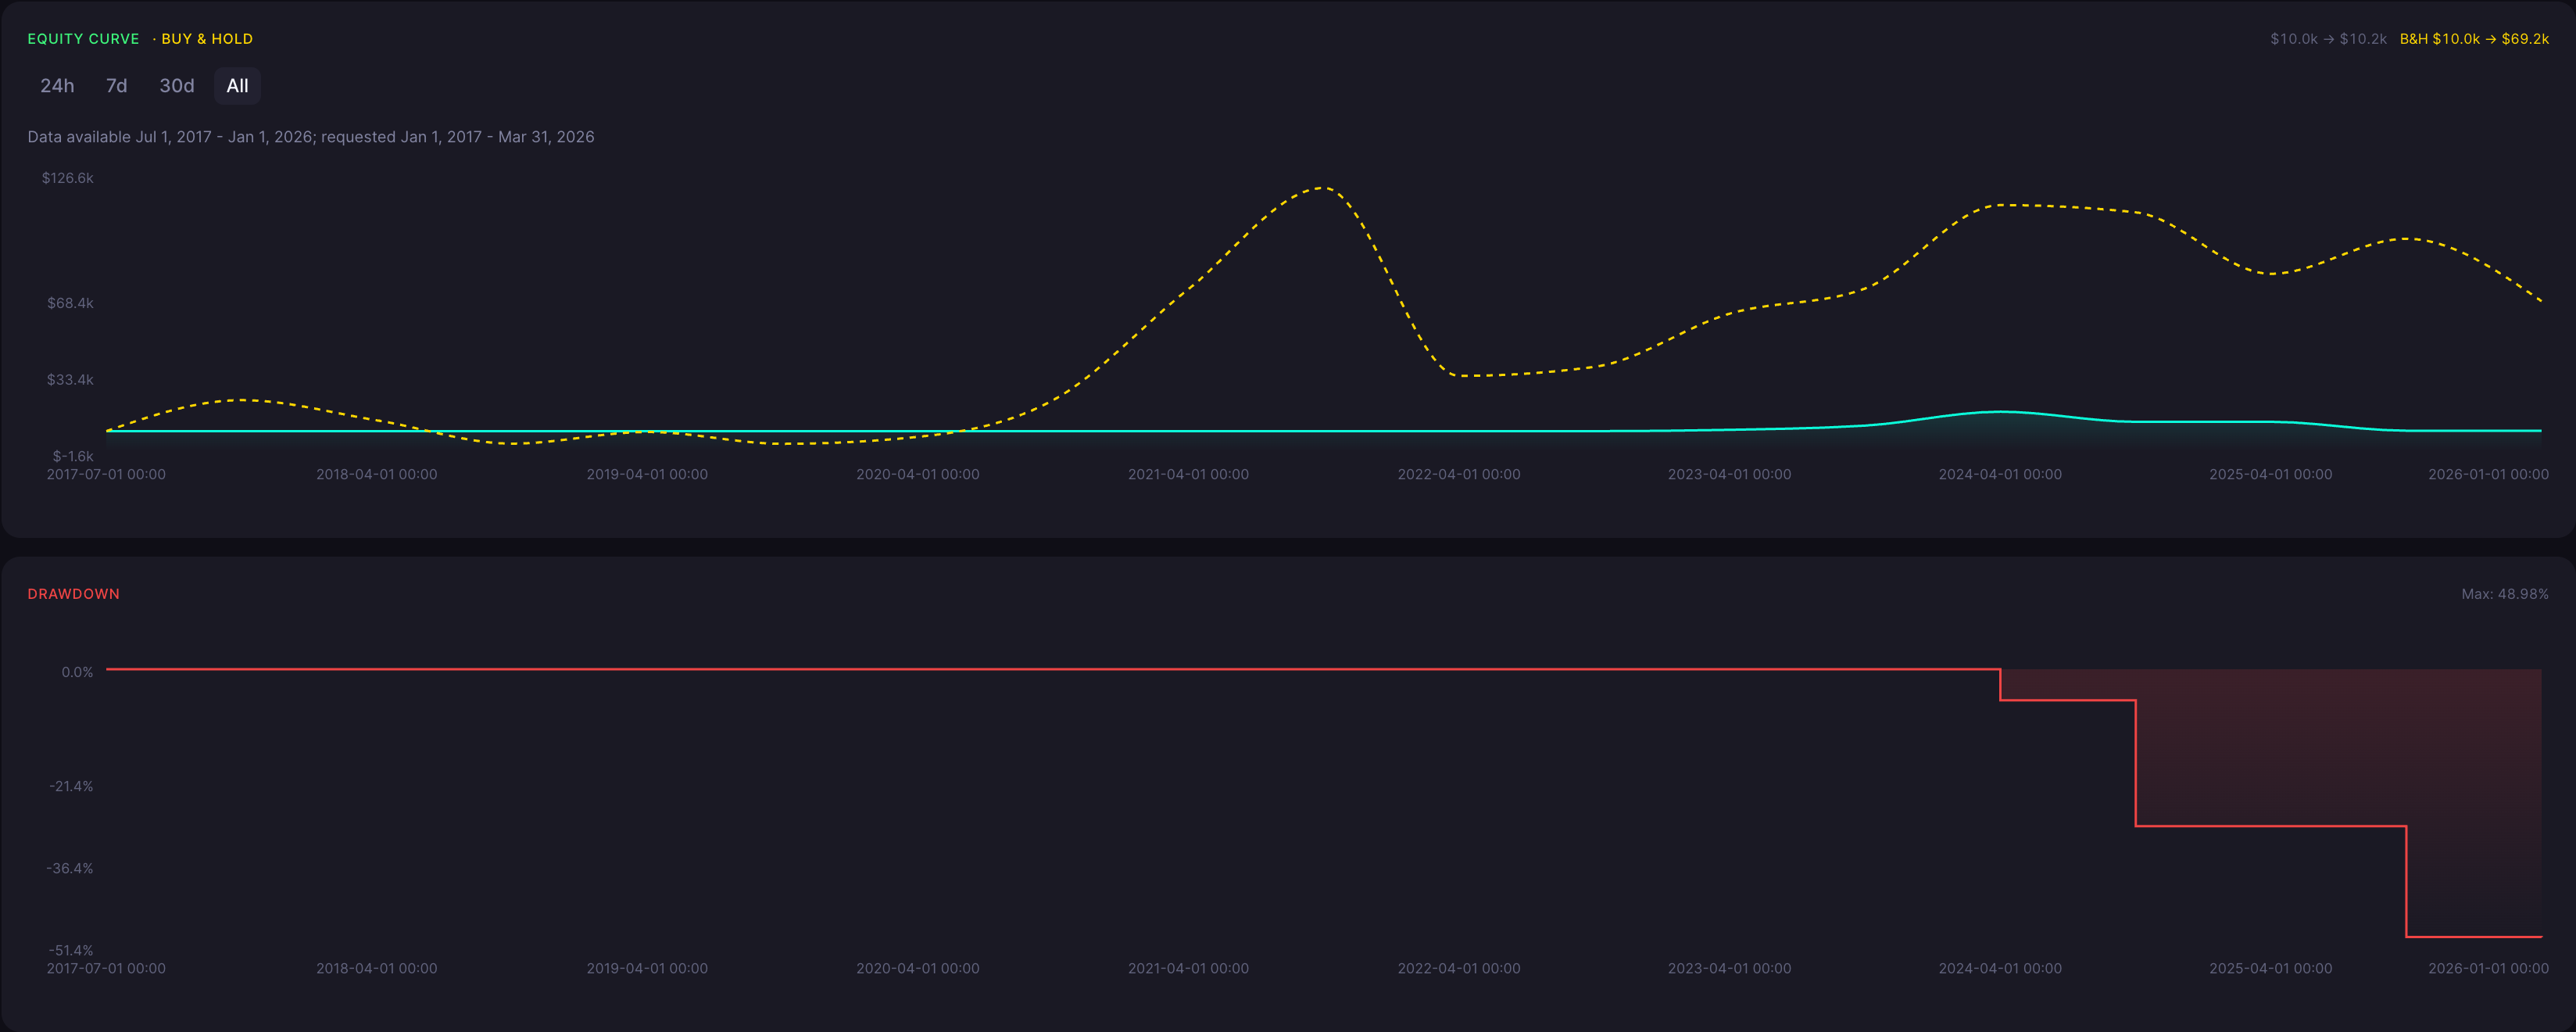
Using three-month ETH/USDT candles, this CoinQuant backtest follows long entries and exits around a Hull Moving Average over 1 Jul 2017 to 1 Jan 2026. The account moved from 10,000.00 USDT to 10,200.77 USDT, producing a return of 2.01% across 2 trades. The ending gain should be read together with the maximum drawdown.
ROI
2.01%
Win Rate
50.00%
Max DD
48.98%
Sharpe
0.13
Profit Factor
1.05
Total Trades
2
Backtest insights
The strategy finished with a return of 2.01%, while its maximum drawdown was 48.98%. The ending gain was therefore accompanied by a much larger decline from an earlier account peak. A win rate of 50.00% across 2 trades is too small a sample to establish consistency. Profit factor of 1.05 adds context to the balance of trading gains and losses, but it does not show that similar results would persist.

Performance may vary depending on market conditions. During trending periods, the strategy may behave differently compared to ranging markets, impacting both returns and drawdowns.
How the Hull Moving Average(10) Crossover Strategy Works
What It Is
The Hull Moving Average combines weighted averages to smooth prices while reducing delay. Here, a 10-period version follows ETH/USDT on three-month candles. It provides a reference line for deciding when to hold a long position.
How Signals Are Generated
Close is the source used to calculate the indicator. The entry occurs when Close crosses above the 10-period Hull Moving Average, and the exit occurs when Close crosses below it. The rule requires a crossing, not simply a price above the line.
When It Works Best
A persistent directional move can give this approach time to follow a trend. That describes the logic behind using a moving average, not a confirmed explanation for the returns in this limited test.
When It Performs Poorly
Sideways trading or sharp reversals can send price back across the line after an entry. Even a more responsive average cannot remove the delays associated with three-month candles, and losses can develop before the exit condition appears.
Strengths

The Hull average aims to balance smoothing with responsiveness.
Crossing rules clearly distinguish an entry from an exit.
The strategy uses a defined indicator length and price source.
Limitations

Three-month candles limit how often the rules can respond.
The 2 trades do not establish dependable performance.
A positive return can coexist with a substantial account decline.
Why Use CoinQuant Instead of Manual Trading or Other Platforms
Choosing the right way to test and execute trading strategies is critical. Below is a comparison between CoinQuant, manual trading, and other platforms to highlight key differences in speed, accuracy, and usability.
CoinQuant is designed specifically for traders who want to validate strategies quickly and reliably without coding. Unlike manual trading or traditional platforms, it allows you to test multiple scenarios, analyze performance instantly, and iterate faster using real data.
Frequently asked questions
How does the Hull Moving Average(10) Crossover strategy perform on ETH/USDT in the 3 Month timeframe?
The performance of the Hull Moving Average(10) Crossover strategy on ETH/USDT in the 3 Month timeframe depends on market conditions. Based on the backtest results above, it achieved a return of 2.01% with a maximum drawdown of 48.98%. Results may vary depending on volatility and overall market trends.
Is the Hull Moving Average(10) Crossover strategy reliable for trading ETH/USDT?
The Hull Moving Average(10) Crossover strategy can be effective when used in the right conditions. For ETH/USDT, it typically performs well in sustained directional trends but may underperform during sideways or rapidly reversing markets. Backtesting helps evaluate its reliability before applying it in live trading.
Why is backtesting important for trading strategies?
Backtesting allows traders to evaluate how a strategy would have performed using historical data. It helps identify strengths, weaknesses, and risk levels before applying the strategy in real markets, reducing the likelihood of unexpected losses.
How can I test the Hull Moving Average(10) Crossover strategy on CoinQuant?
You can use CoinQuant to build and backtest the Hull Moving Average(10) Crossover strategy without coding. Simply select your asset, define your strategy rules, and run a backtest to view detailed performance metrics instantly.
What are the best settings for the Hull Moving Average(10) Crossover strategy on 3 Month?
The best settings for the Hull Moving Average(10) Crossover strategy depend on the asset and timeframe. Traders often adjust parameters based on volatility and trading style. Using a backtesting platform like CoinQuant allows you to test different configurations and identify what works best.