
Backtest Results
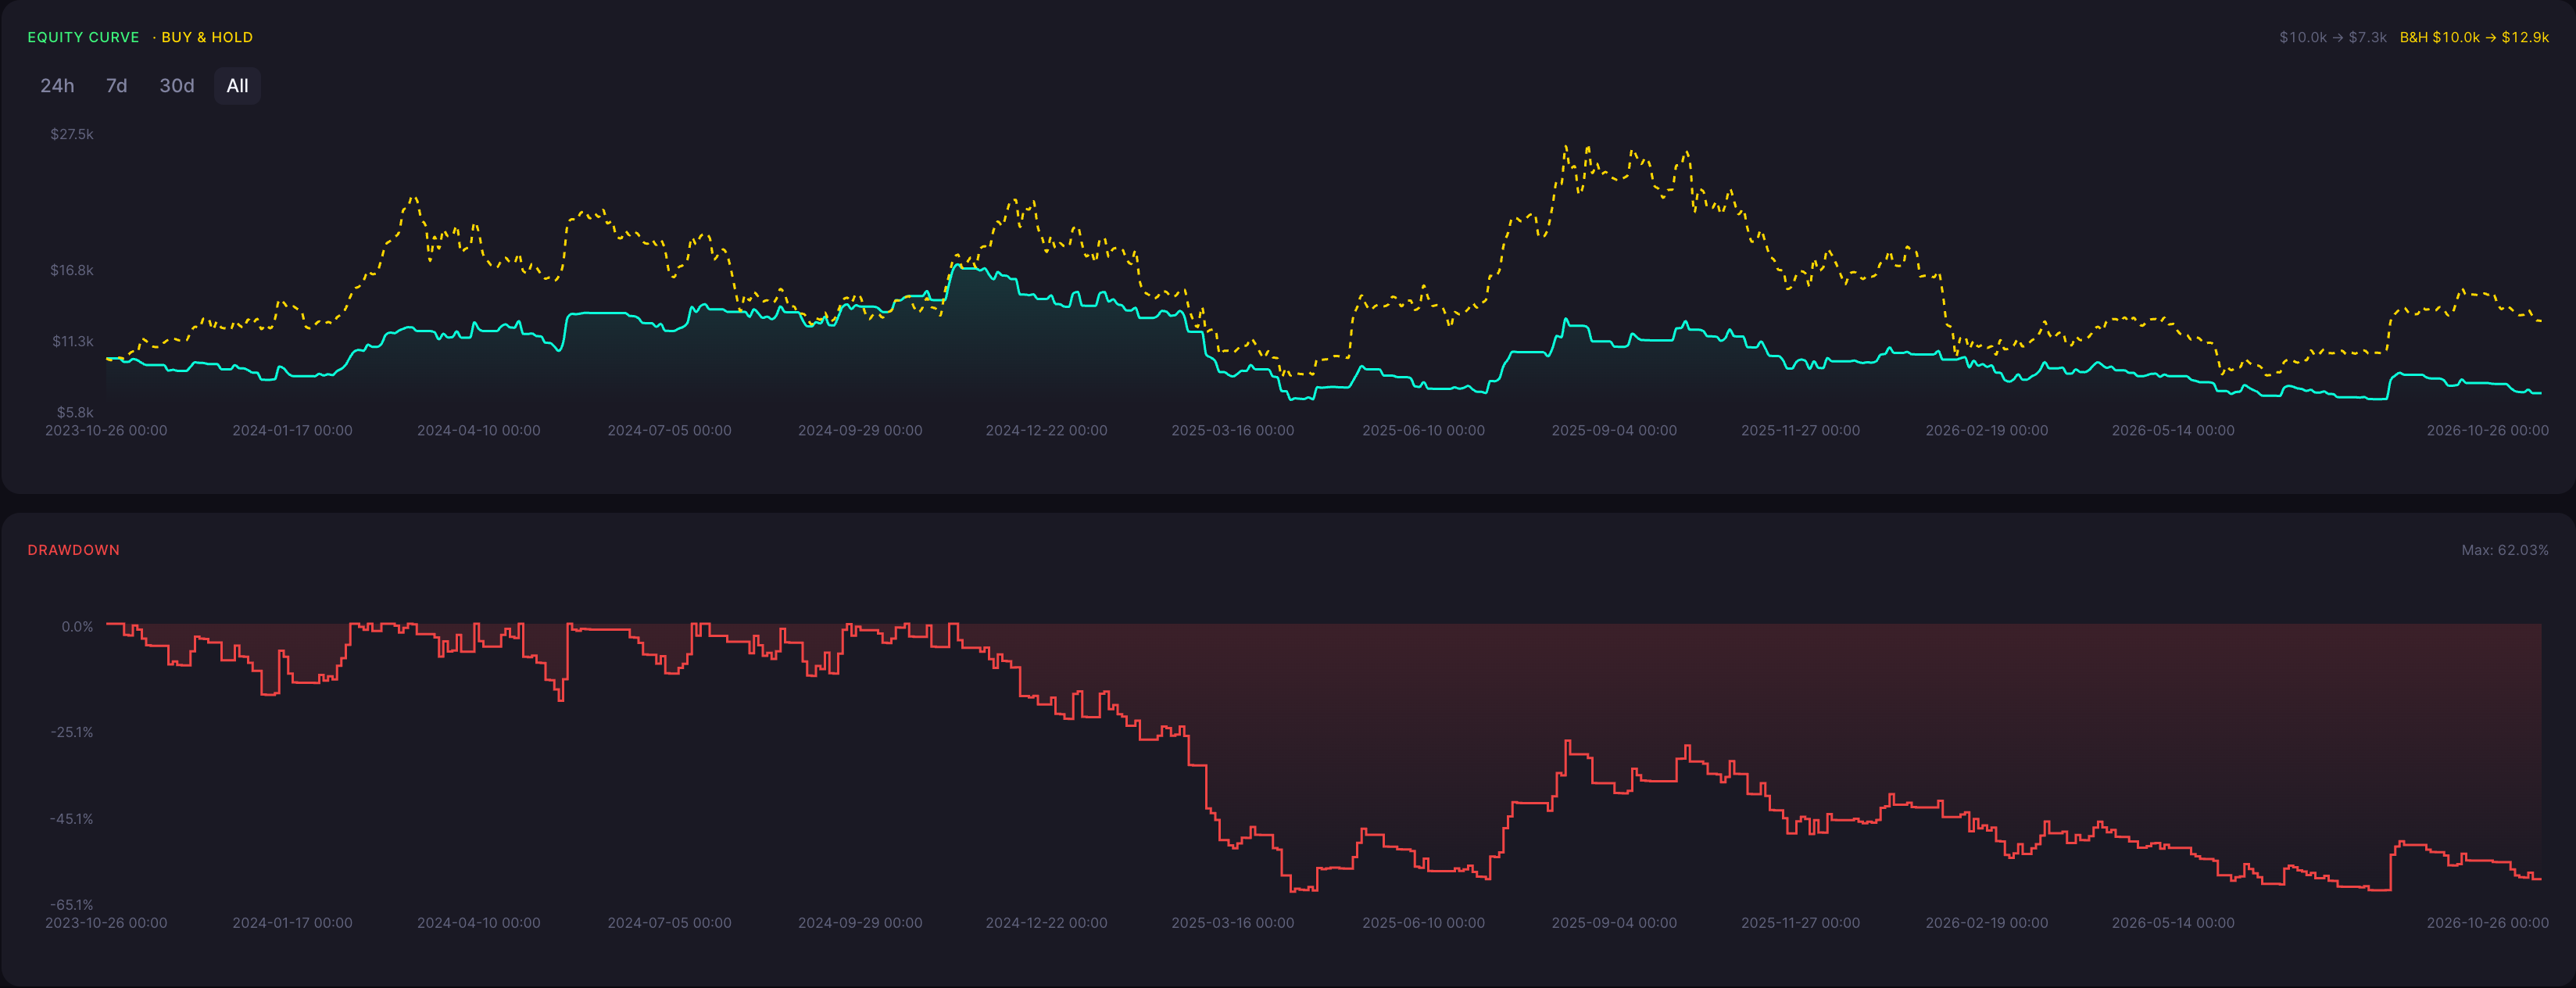
This backtest ended below its starting capital. Equity began at 10,000.00 USDT and finished at 7,332.50 USDT, a total return of -26.67%. The deepest peak-to-trough decline was 62.03%. Of 136 trades, 30.15% were winners, and the profit factor was 0.92, meaning gross profits were smaller than gross losses over the run. Every trade was long: the Long Ratio is 1.00 and the Short Ratio is 0.00. Test period: 26 Oct 2023 to 26 Oct 2026.
ROI
-26.67%
Win Rate
30.15%
Max DD
62.03%
Sharpe
-0.01
Profit Factor
0.92
Total Trades
136
Backtest insights
In this backtest, the strategy returned -26.67%, reducing 10,000.00 USDT to 7,332.50 USDT across 136 trades. Maximum drawdown reached 62.03%, and at the end of the test on 26 Oct 2026, equity was still 59.10% below a peak recorded on 11 Nov 2024. Winners averaged larger than losers (payoff ratio 2.14), yet the 30.15% win rate left the profit factor at 0.92. This is one asset, one timeframe and one window, so the sample cannot show how the rules would behave elsewhere, and this page does not diagnose why the result occurred.

Performance may vary depending on market conditions. During trending periods, the strategy may behave differently compared to ranging markets, impacting both returns and drawdowns.
Strategy Explanation
What It Is
The Double Exponential Moving Average (DEMA) is a trend indicator built from exponential moving averages and designed to respond to price changes with less lag than a standard EMA of the same length. This strategy, saved as ETH 1d Close vs DEMA(10) Crossover, compares the daily closing price of ETHUSDT with a 10-period DEMA calculated on closing prices.
How Signals Are Generated
Entry: when Close crosses above DoubleExponentialMovingAverage(period=10, source=close), enter long with a market order.
Exit: when Close crosses below DoubleExponentialMovingAverage(period=10, source=close), exit the long position with a market order.
There are no additional filters, short positions, stop losses or profit targets.
When It Works Best
General theory, not demonstrated by this run. Close-versus-DEMA crossovers tend to suit markets with sustained, directional trends.
When It Performs Poorly
General theory, not a diagnosis of this run. In choppy or range-bound markets, price can cross a short moving average back and forth many times, producing a series of small losing trades.
Strengths

Transparent rules: two crossover conditions with one indicator and one parameter, so every trade can be traced to a specific signal.
Defined exposure: long-only with one open position at a time and no leverage beyond 100% of current equity.
Systematic exits: the exit rule is fixed in advance, so positions are closed by the same logic that opens them rather than by discretion.
Limitations

Unknown costs: trading fee and slippage settings were not provided, so the real cost of trading is unknown, not zero. The test shows total fees of 2,825.91, but this figure does not show the fee rates used or how all trading costs were calculated. Live execution costs may differ.
Test period: the backtest covers 26 Oct 2023 to 26 Oct 2026. This does not confirm that the price history has no gaps. The results list 1197 bars processed and 1097 sampled performance points, which are not the underlying price candles; neither figure documents whether the candle history is continuous, and how the indicators were prepared at the start of the test remains undocumented. Trade dates describe observed activity, not tested-data boundaries.
Sample size and generalization: 136 trades on one asset, one timeframe and one window is a limited sample. It does not establish robustness, optimality or how the rules would perform on other periods, timeframes or markets.
Why Use CoinQuant Instead of Manual Trading or Other Platforms
Choosing the right way to test and execute trading strategies is critical. Below is a comparison between CoinQuant, manual trading, and other platforms to highlight key differences in speed, accuracy, and usability.
CoinQuant is designed specifically for traders who want to validate strategies quickly and reliably without coding. Unlike manual trading or traditional platforms, it allows you to test multiple scenarios, analyze performance instantly, and iterate faster using real data.
Frequently asked questions
How does the DEMA strategy perform on ETH in the daily timeframe?
The performance of the DEMA strategy on ETH in the daily timeframe depends on market conditions. Based on the backtest results above, it achieved a return of -26.67% with a maximum drawdown of 62.03%. Results may vary depending on volatility and overall market trends.
Is the DEMA strategy reliable for trading ETH?
The DEMA strategy can be effective when used in the right conditions. For ETH, it typically performs well in sustained directional trends (general theory, not measured in this run) but may underperform during choppy or sideways markets (general theory, not measured in this run). Backtesting helps evaluate its reliability before applying it in live trading.
Why is backtesting important for trading strategies?
Backtesting allows traders to evaluate how a strategy would have performed using historical data. It helps identify strengths, weaknesses, and risk levels before applying the strategy in real markets, reducing the likelihood of unexpected losses.
How can I test the DEMA strategy on CoinQuant?
You can use CoinQuant to build and backtest the DEMA strategy without coding. Simply select your asset, define your strategy rules, and run a backtest to view detailed performance metrics instantly.
What are the best settings for the DEMA strategy on daily?
The best settings for the DEMA strategy depend on the asset and timeframe. Traders often adjust parameters based on volatility and trading style. Using a backtesting platform like CoinQuant allows you to test different configurations and identify what works best.