
Backtest Results
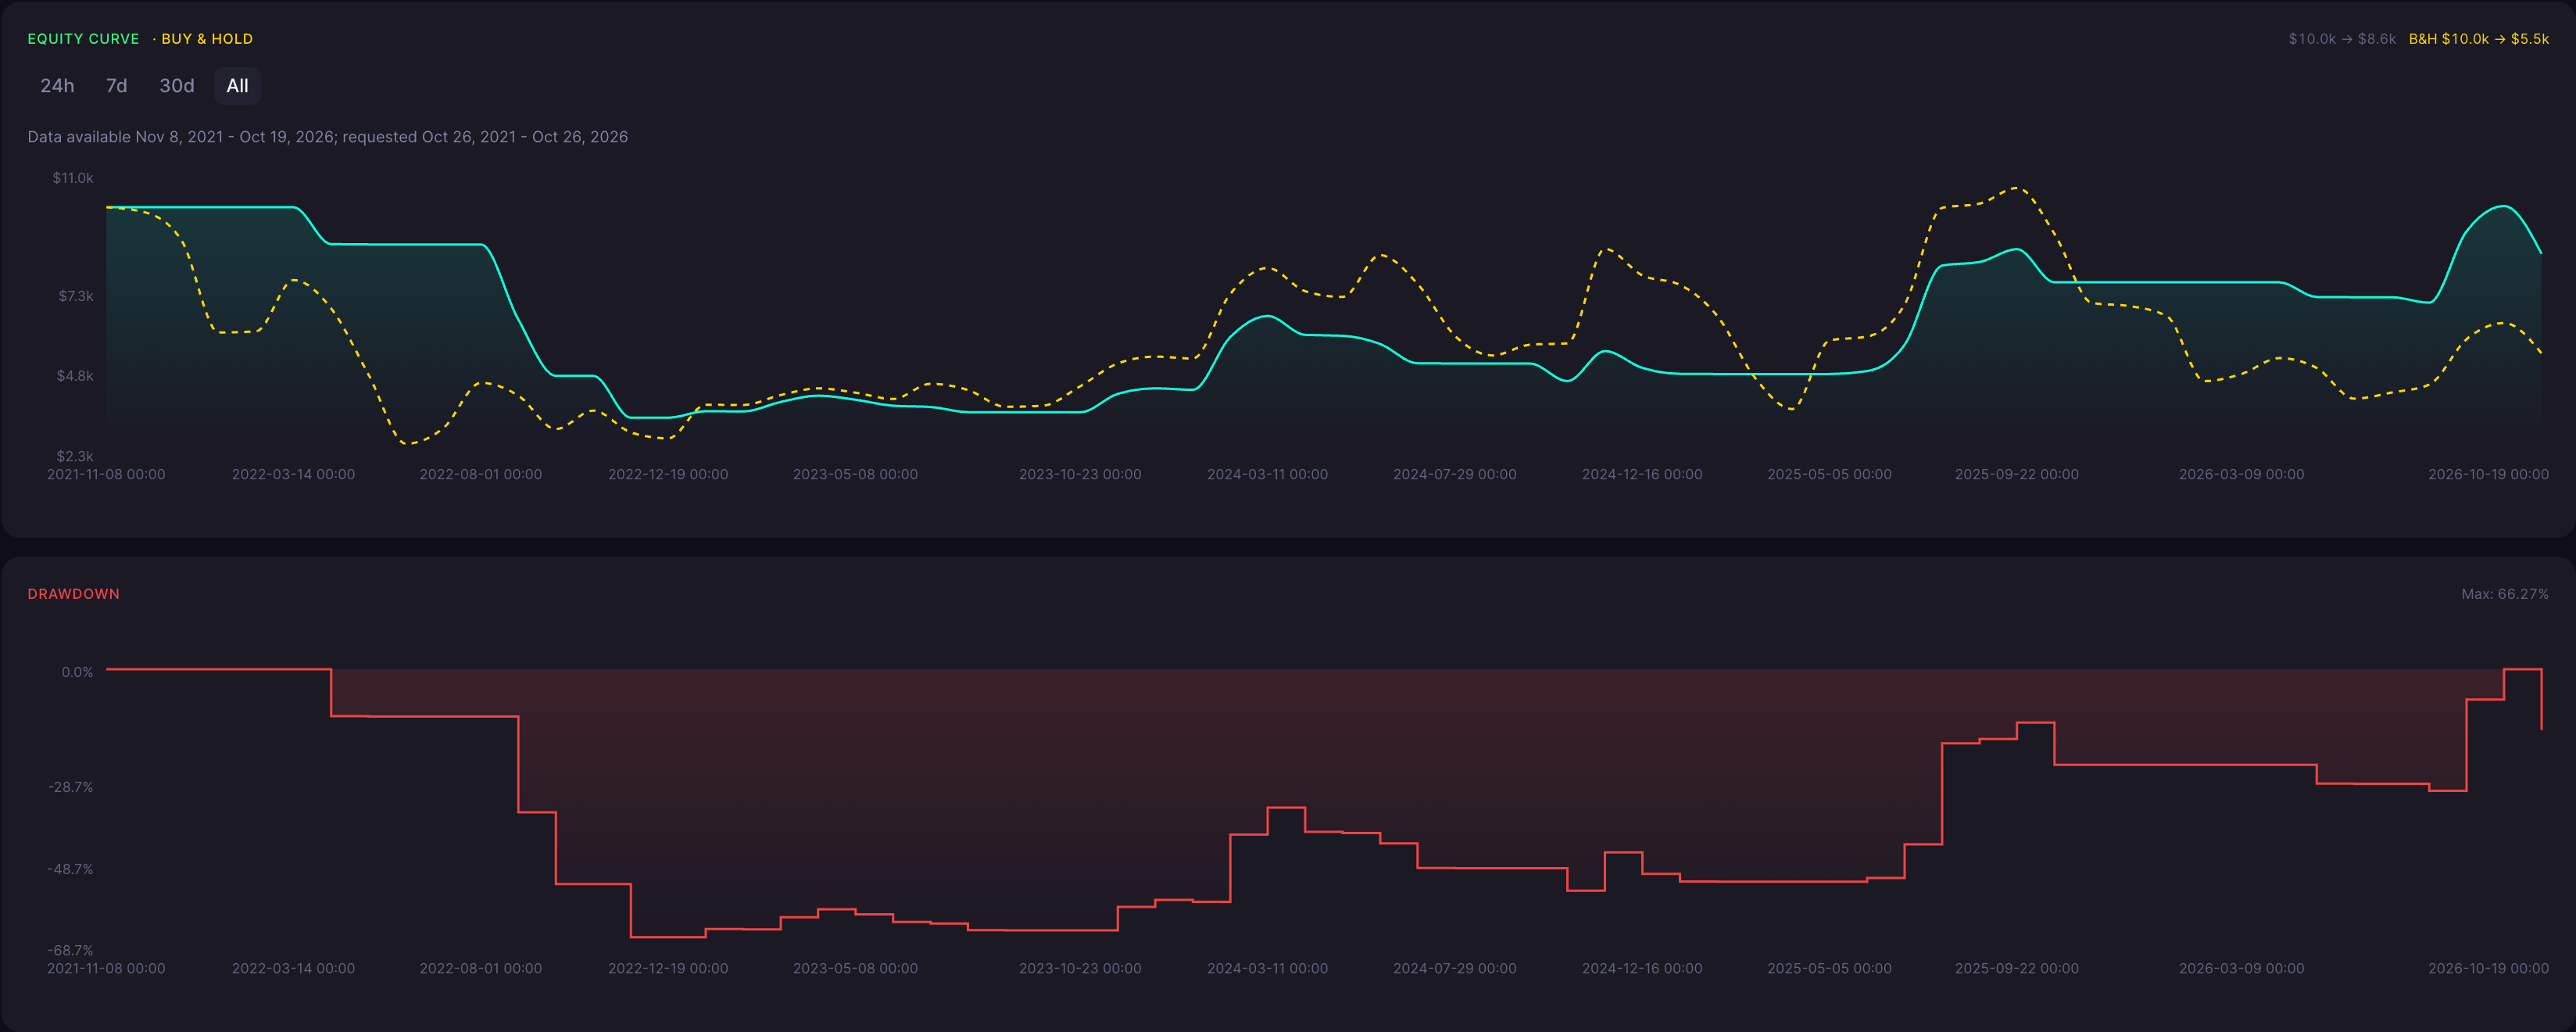
Result summary: from November 8 2021 to October 19 2026, a shorter period than planned because market data was limited, the 2-week WMA crossover was unprofitable, with a -14.49% total return. It completed 13 trades with a 38.46% win rate and a profit factor of 0.83, meaning gross losses exceeded gross gains. The Sharpe ratio was 0.13 and the maximum drawdown was 66.27%, a deep decline from peak equity. Reported trade activity ran from March 14, 2022 to October 19, 2026. The report lists a buy-and-hold final value of 5,458.86 over November 8 2021 to October 19 2026; the strategy's initial capital setting was 10,000.00 USDT. With 13 trades, this is a small sample from one historical path and one parameter set.
ROI
-14.49%
Win Rate
38.46%
Max DD
66.27%
Sharpe
0.13
Profit Factor
0.83
Total Trades
13
Backtest insights
Result summary: from November 8 2021 to October 19 2026, a shorter period than planned because market data was limited, the 2-week WMA crossover was unprofitable, with a -14.49% total return. It completed 13 trades with a 38.46% win rate and a profit factor of 0.83, meaning gross losses exceeded gross gains. The Sharpe ratio was 0.13 and the maximum drawdown was 66.27%, a deep decline from peak equity. Reported trade activity ran from March 14, 2022 to October 19, 2026. The report lists a buy-and-hold final value of 5,458.86 over November 8 2021 to October 19 2026; the strategy's initial capital setting was 10,000.00 USDT. With 13 trades, this is a small sample from one historical path and one parameter set.

Performance may vary depending on market conditions. During trending periods, the strategy may behave differently compared to ranging markets, impacting both returns and drawdowns.
Strategy Explanation
What It Is
The rules are a plain price and moving average crossover with no additional logic. The strategy enters long when the 2-week Close crosses above the 10-period WMA calculated on Close, and exits when the Close crosses below that WMA. There are no extra conditions, filters, stop losses, profit targets or short positions. The run used 10,000.00 USDT initial capital with each position sized at 100.00% of current equity, a maximum of one open entry, spot asset type and the Binance exchange. On 2-week candles, each signal reflects a longer stretch of price action, so the crossover responds slowly and can stay in or out of the market for extended periods.
How Signals Are Generated
Enter long when Close crosses above WMA(10); exit when Close crosses below WMA(10). The saved CoinQuant crosses-above and crosses-below rules define how an equal value at the crossover boundary is handled. There are no extra filters, shorts, discretionary entries or added stop/target conditions.
When It Works Best
Sustained directional movement can favor a moving-average crossover. This is a general strategy characteristic, not a confirmed explanation of this run's result.
When It Performs Poorly
Repeated crossings in sideways or rapidly reversing markets can create whipsaws and costs. The historical outcome must be read with that risk in mind.
Strengths

The rules are a plain price and moving average crossover with no additional logic.
The strategy enters long when the 2-week Close crosses above the 10-period WMA calculated on Close, and exits when the Close crosses below that WMA.
There are no extra conditions, filters, stop losses, profit targets or short positions.
Limitations

Market data availability clipped this run. The test ran from 8 Nov 2021 to 19 Oct 2026, so results do not represent the full planned period. Limited market data shortened the test period.
The backtest reported 232 bars consumed and 130 performance observations; these counts are reported as supplied, are not a measure of candle resolution, and do not prove raw data continuity. How the indicator was prepared at the start of the test has not been independently checked.
Maker and taker fees and slippage were not provided, so it is unknown whether or how trading costs are reflected in the results. The sample contains 13 trades from a single parameter set on a single asset.
Why Use CoinQuant Instead of Manual Trading or Other Platforms
Choosing the right way to test and execute trading strategies is critical. Below is a comparison between CoinQuant, manual trading, and other platforms to highlight key differences in speed, accuracy, and usability.
CoinQuant is designed specifically for traders who want to validate strategies quickly and reliably without coding. Unlike manual trading or traditional platforms, it allows you to test multiple scenarios, analyze performance instantly, and iterate faster using real data.
Frequently asked questions
Was the ETH 2-week WMA crossover profitable?
No. It recorded a -14.49% total return over the test period of November 8 2021 to October 19 2026 with a profit factor of 0.83 and a 66.27% maximum drawdown.
How many trades did the backtest make?
13 trades, with a 38.46% win rate. Reported trade activity ran from March 14, 2022 to October 19, 2026.
Does this backtest cover the full five-year requested window?
No. The requested range was October 26, 2021 to October 26, 2026, but market data availability clipped it to November 8, 2021 through October 19, 2026.
Are trading fees and slippage included?
Unknown. Maker and taker fees were not provided, which does not mean they were zero, and slippage is unknown.
Does this predict future returns?
No. Backtest performance is historical. Test assumptions, costs and data limitations matter, and future results may differ.