
Backtest Results
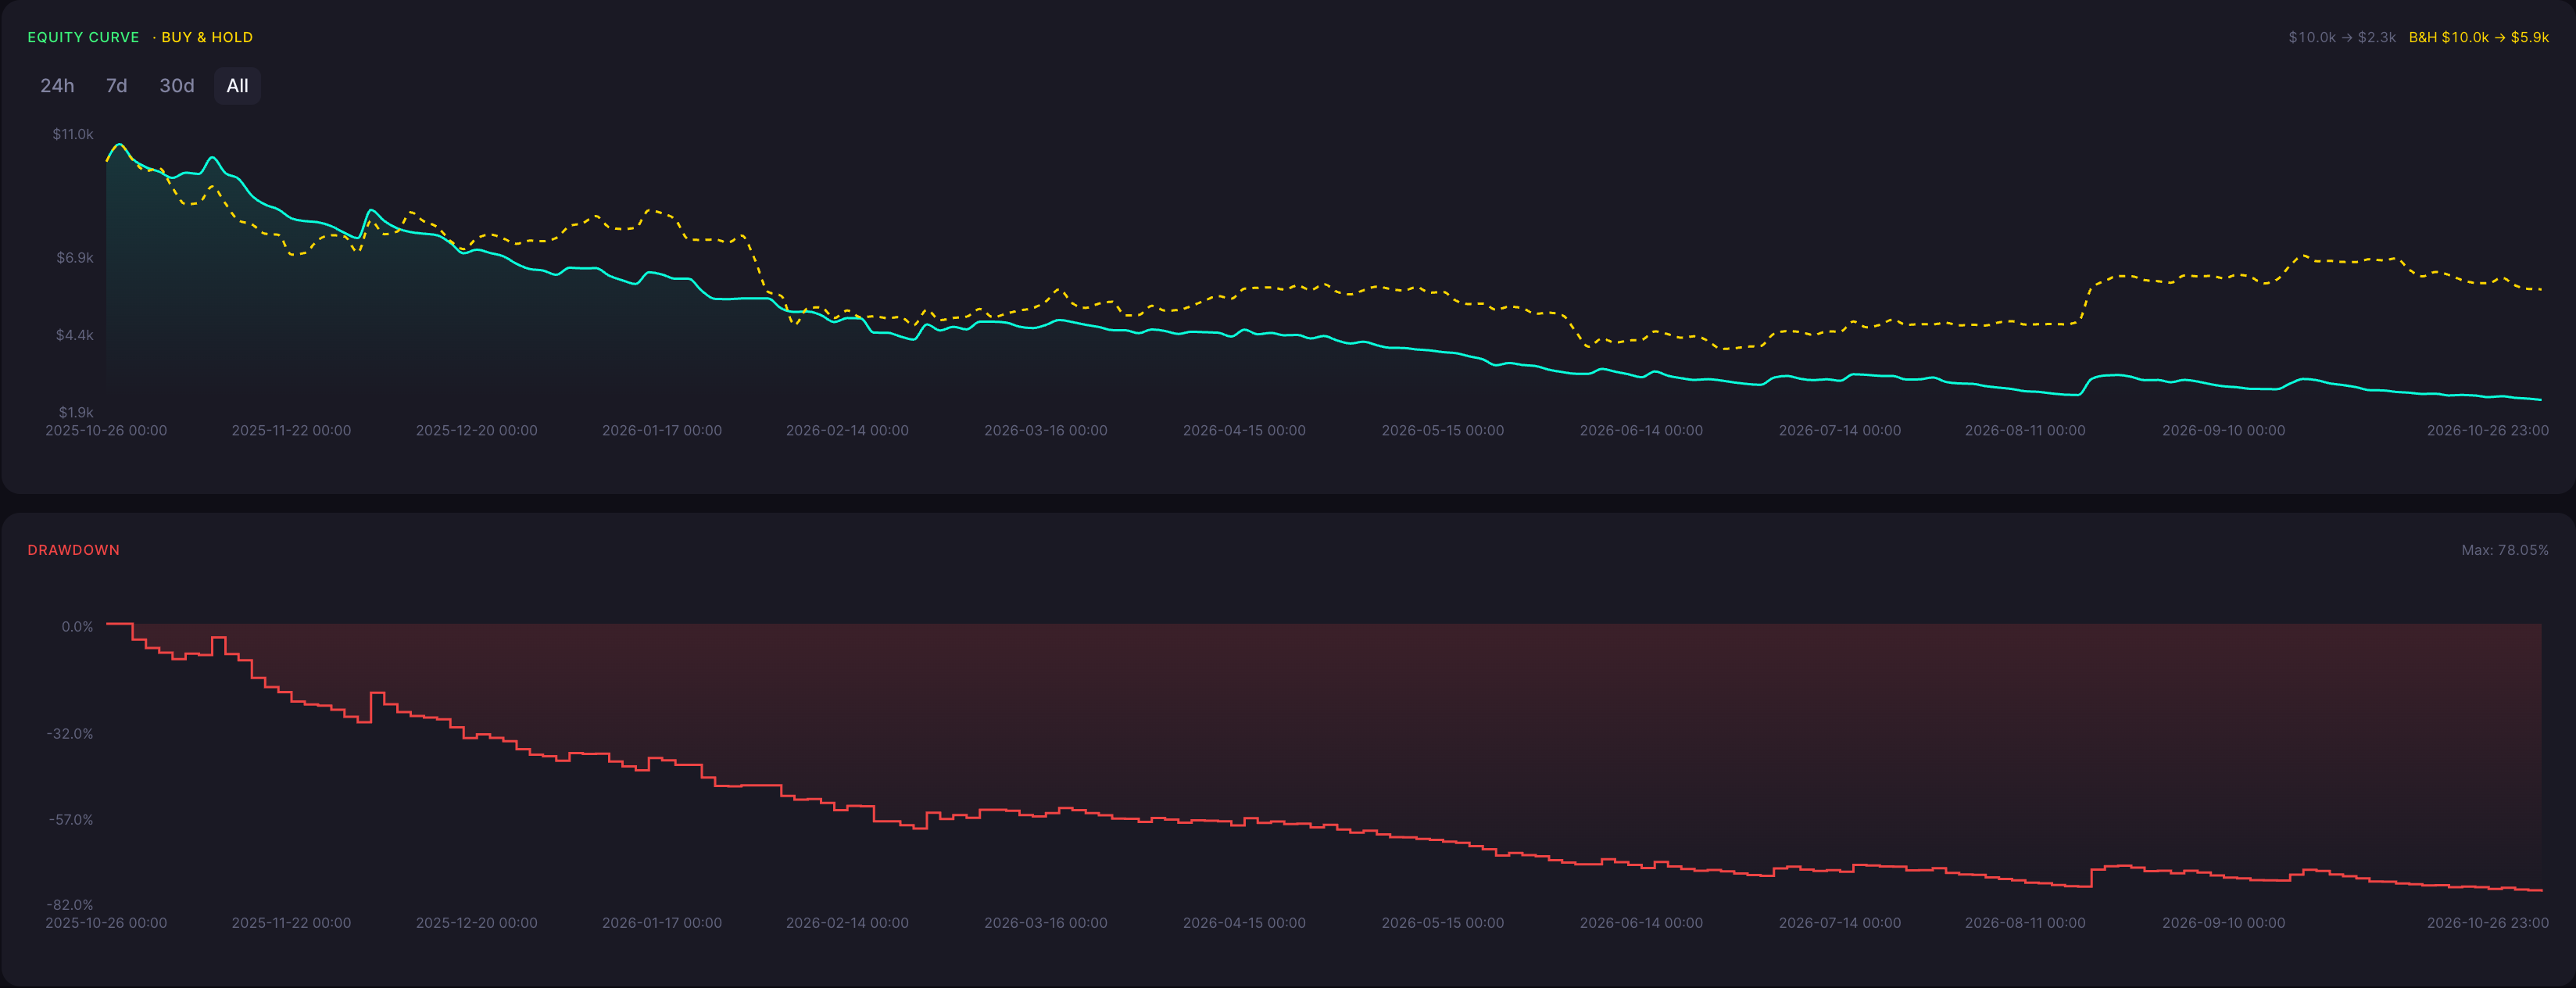
The 1 hour ETHUSDT test recorded a large historical loss of -76.81%, with maximum drawdown of 78.05%. Test dates: 26 Oct 2025 to 26 Oct 2026. Test period: 26 Oct 2025 to 26 Oct 2026. No problems with the date range were flagged for this test. This does not confirm that the full price history is available.
ROI
-76.81%
Win Rate
15.86%
Max DD
78.05%
Sharpe
-3.14
Profit Factor
0.55
Total Trades
637
Backtest insights
A -76.81% return and 78.05% maximum drawdown make the downside clear in this hourly test. Its 637 trades had a reported win rate of 15.86%, while the profit factor was 0.55 and Sharpe ratio was -3.14. These are overall historical results. They do not show that signals ran consistently or point to a specific market condition. They cannot determine whether costs or particular price patterns caused the loss. The saved implementation needs to be distinguished from the requested indicator name.

Performance may vary depending on market conditions. During trending periods, the strategy may behave differently compared to ranging markets, impacting both returns and drawdowns.
How the RMA Strategy Works
What It Is
RMA here refers to the requested Running Moving Average, set to period 10 with Close as its source. In the saved strategy, the series is called RelativeMovingAverage. Using the same period and data source does not mean the formula is the same. Acceptance of the disclosed 72-field difference class was acceptance of risk, not mathematical equivalence.
How Signals Are Generated
The request enters long when Close crosses above the 10-period Running Moving Average and exits when Close crosses below it. The saved entry goes long when Close crosses above the Relative Moving Average; the saved exit closes the long when Close crosses below it. Both use market orders on the 1 hour timeframe. These are saved conditions, not proof that every crossing executed. General oscillator and divergence settings also exist in the saved strategy; their presence does not prove an extra measured signal or that they have no effect.
When It Works Best
As general theory, a moving-average entry can be useful when price continues upward rather than returning across the reference soon after entry. This behavior was not measured in this run. The hourly result does not show which environments, if any, supported a repeatable advantage.
When It Performs Poorly
General theory suggests that a crossover approach may struggle when price repeatedly changes direction around its reference or falls before the exit responds. Neither mechanism was measured in this run. The aggregate loss alone cannot identify which price behavior or execution detail mattered.
Strengths

A fixed 10-period reference gives the requested strategy a clearly stated parameter.
The saved hourly strategy shows its Close-based entry and exit rules for review.
Long-only entry and exit actions provide a bounded rule description without adding a short strategy.
Limitations

This single test returned -76.81% with 78.05% maximum drawdown. It does not establish reliability, optimal settings or future profitability.
Trading costs are unknown: fees and slippage were not provided. These fields establish neither inclusion nor exclusion of costs, and they do not mean zero costs.
The requested Running Moving Average and the saved Relative Moving Average are not confirmed to be mathematically the same. General oscillator and divergence settings are not confirmed to have no effect. How the test started its indicator calculations is not documented; performance points, bar counts and elapsed dates do not prove that the price history is complete or continuous.
Why Use CoinQuant Instead of Manual Trading or Other Platforms
Choosing the right way to test and execute trading strategies is critical. Below is a comparison between CoinQuant, manual trading, and other platforms to highlight key differences in speed, accuracy, and usability.
CoinQuant is designed specifically for traders who want to validate strategies quickly and reliably without coding. Unlike manual trading or traditional platforms, it allows you to test multiple scenarios, analyze performance instantly, and iterate faster using real data.
Frequently asked questions
How does the RMA strategy perform on ETH in the 1 hour timeframe?
The performance of the RMA strategy on ETH in the 1 hour timeframe depends on market conditions. Based on the backtest results above, it achieved a return of -76.81% with a maximum drawdown of 78.05%. Results may vary depending on volatility and overall market trends.
Is the RMA strategy reliable for trading ETH?
The RMA strategy can be effective when used in the right conditions. For ETH, it typically performs well in sustained directional trends (general theory, not measured in this run) but may underperform during choppy or sideways markets (general theory, not measured in this run). Backtesting helps evaluate its reliability before applying it in live trading.
Why is backtesting important for trading strategies?
Backtesting allows traders to evaluate how a strategy would have performed using historical data. It helps identify strengths, weaknesses, and risk levels before applying the strategy in real markets, reducing the likelihood of unexpected losses.
How can I test the RMA strategy on CoinQuant?
You can use CoinQuant to build and backtest the RMA strategy without coding. Simply select your asset, define your strategy rules, and run a backtest to view detailed performance metrics instantly.
What are the best settings for the RMA strategy on 1 hour?
The best settings for the RMA strategy depend on the asset and timeframe. Traders often adjust parameters based on volatility and trading style. Using a backtesting platform like CoinQuant allows you to test different configurations and identify what works best.