
Live Backtest Results
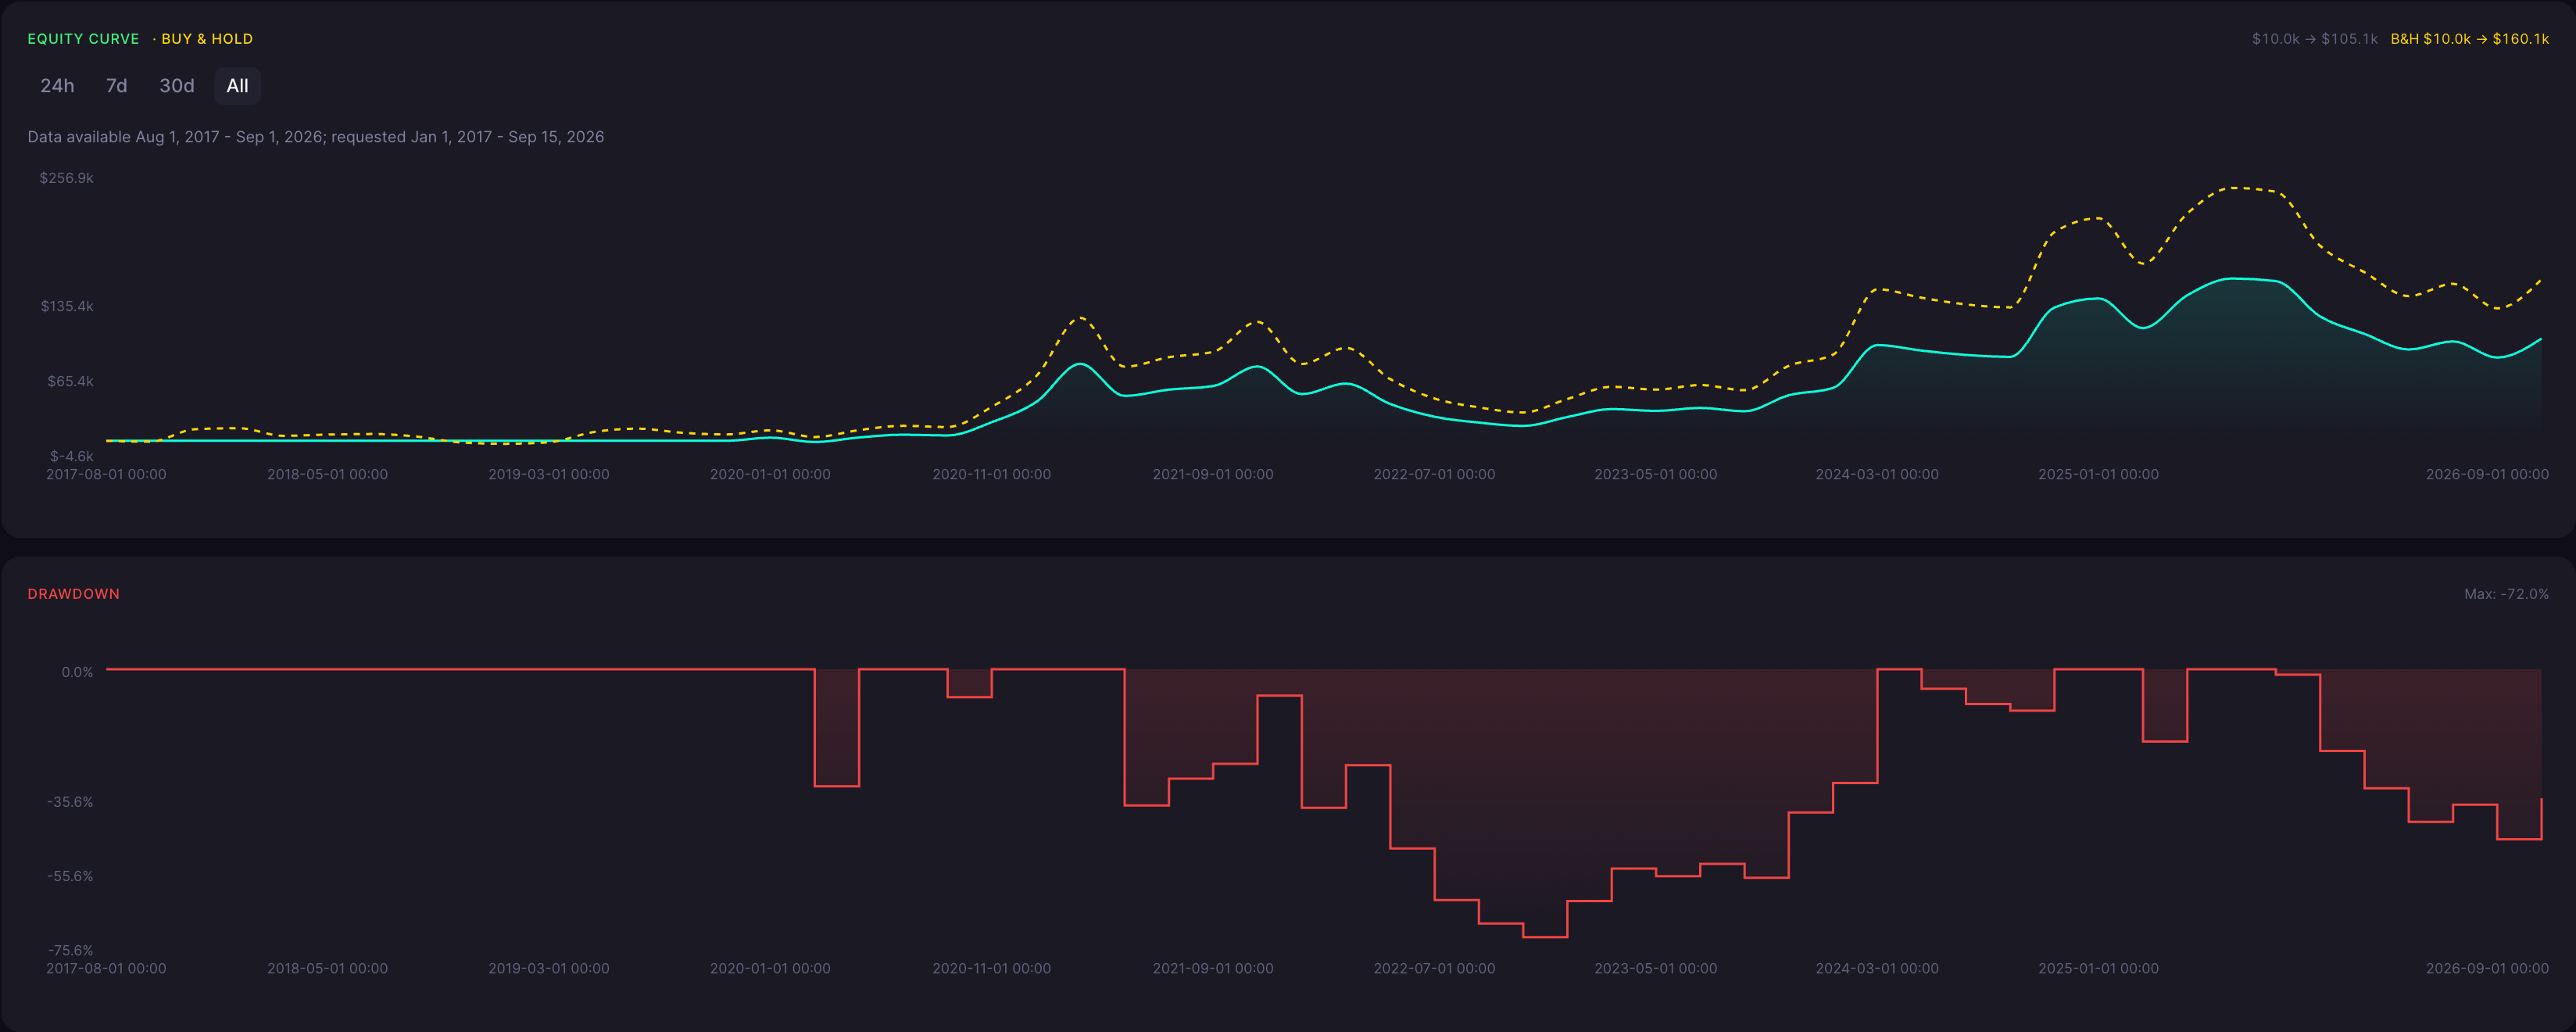
This corrected backtest analyzes the BTC Takuri strategy over the 1 month timeframe. The exact Strategy Prompt below defines the corrected executable configuration, including its entry and exit rules and the selected backtest window.
ROI
950.89%
Win Rate
100.00%
Max DD
73.01%
Sharpe
0.72
Profit Factor
N/A
Total Trades
1
Backtest insights
The Takuri strategy generated a total return of 950.89% over the 1 month timeframe. With a maximum drawdown of 73.01% and a win rate of 100.00% across 1 trades, the corrected backtest ran from 2017-01-01 to 2026-09-15. The selected strategy version and backtest identifiers are recorded in the configuration below.

Performance may vary depending on market conditions. During trending periods, the strategy may behave differently compared to ranging markets, impacting both returns and drawdowns.
How the Takuri Strategy Works
What It Is
The Takuri candle pattern is a long-lower-shadow reversal pattern often treated as a stronger form of downside rejection. This test uses the Takuri pattern as the long trigger and a Bearish Engulfing pattern as the exit reference. The page reports a real CoinQuant backtest on BTC/USDT 1 month data.
How Signals Are Generated
The corrected configuration is defined by the exact Strategy Prompt below. It uses the selected 1 month timeframe and runs from 2017-01-01 to 2026-09-15.
Strategy Prompt
Long-only BTCUSDT on the 1-month monthly timeframe using bars. Do not use any named candle detector, FuzzyCandlesticks entry, Hammer, Takuri detector, generic candlestick detector, indicator, or proxy for the entry. Implement one detector-free current-bar Takuri-style OHLC rejection entry as an AND group of only raw Open, High, Low, and Close comparisons. Require the nonzero real body by setting the absolute percentage distance between Open and Close greater than 0.01% and at most 10%. Require the materially long lower shadow by requiring Low to be at least 8% below Open AND at least 8% below Close. Require the minimal upper shadow by requiring High to be no more than 8% above Open AND no more than 8% above Close. These duplicate comparisons deliberately express Low below min(Open, Close) and High near max(Open, Close) without min or max functions. All entry conditions must be simultaneous on the same current monthly candle, and enter long at that qualifying candle close. Exit the long only when a Bearish Engulfing pattern is detected. The entry schema must contain only raw High, Low, Open, and Close comparison conditions, not a detector. Backtest the full available BTCUSDT monthly history from 2017-01-01 to 2026-09-15.
When It Works Best
This strategy tends to work best when a deep lower shadow marks seller exhaustion and buyers continue to lift BTC/USDT after the signal. The 1 month timeframe captures a distinct market rhythm, so the same indicator can behave differently across horizons.
When It Performs Poorly
The strategy struggles when a long lower shadow is only a temporary bounce inside a larger decline or high-volatility range.
Strengths

Tests a specific downside-rejection candle
Fits a natural long-only reversal hypothesis
Uses transparent pattern-based rules
Limitations

Takuri signals need follow-through to matter
Failed reversals can draw down quickly
Sparse signals may reduce sample size on higher timeframes
Why Use CoinQuant Instead of Manual Trading or Other Platforms
Choosing the right way to test and execute trading strategies is critical. Below is a comparison between CoinQuant, manual trading, and other platforms to highlight key differences in speed, accuracy, and usability.
CoinQuant is designed specifically for traders who want to validate strategies quickly and reliably without coding. Unlike manual trading or traditional platforms, it allows you to test multiple scenarios, analyze performance instantly, and iterate faster using real data.
Frequently asked questions
How does the Takuri strategy perform on BTC/USDT in the 1 month timeframe?
In this corrected backtest, the Takuri strategy on the 1 month timeframe generated a return of 950.89% with a maximum drawdown of 73.01% and a win rate of 100.00% across 1 trades. These results are based on historical backtest data and actual performance may vary.
What is the Takuri indicator?
The Takuri candle pattern is a long-lower-shadow reversal pattern often treated as a stronger form of downside rejection. This test uses the Takuri pattern as the long trigger and a Bearish Engulfing pattern as the exit reference.
Why is backtesting important for trading strategies?
Backtesting evaluates how a strategy would have performed on historical data before risking real capital. It reveals metrics like ROI, drawdown, and win rate that show whether a strategy has a genuine edge.
How can I test the Takuri strategy on CoinQuant?
Paste the exact strategy prompt from this page into CoinQuant, select BTC/USDT and the 1 month timeframe, and CoinQuant generates a full backtest with performance metrics, no coding required.
What are the best settings for the Takuri strategy on the 1 month timeframe?
Optimal settings depend on the indicator parameters, timeframe, market regime, and trading objective. The default tested here is the exact rule shown in the strategy prompt. CoinQuant lets you test parameter variations to find the best fit for the 1 month timeframe.
Explore similar strategies
