
Crypto Day Trading Strategy: Why Backtesting Short-Term Setups Matters More Than You Think
Day traders are the most disciplined people in crypto about their setups and the least disciplined about their evidence. They can explain exactly why they entered a trade, and they cannot tell you whether that entry has ever made money over a statistically meaningful sample. The reason is structural: short-term strategies generate hundreds of signals, and no human memory can hold a hundred-signal track record.
That is why backtesting matters more for day traders than for anyone else in the market. The strategies that need validation the most are the ones that trade the most, because frequency multiplies both the opportunity and the cost. This article explains what makes short-term validation different, and what to check before you trust a day trading backtest.
Why Frequency Changes the Validation Game
A swing strategy trading 20 times a year can survive small data flaws: a few wrong signals barely move the average. A day trading strategy trading 500 times a year amplifies every flaw. Wrong fills, missing fees, and data gaps repeat hundreds of times, and each repetition costs money.
Frequency also fixes the sample-size problem in your favor. Twenty trades a year means years of waiting for evidence. A 15-minute strategy can produce a statistically meaningful trade count in months, which means day traders can actually learn faster, but only if the backtest is honest enough to learn from.
The Fee Problem Is a Day Trading Problem
Here is the arithmetic that ends most day trading strategies: costs apply per side, per trade. A strategy on a 15-minute chart might trade 30 times a month. At a 0.1% taker fee per side, that is roughly 0.2% of equity in costs per round trip, about 6% per month and more than half the account per year before a single profitable trade.
Backtests that ignore fees or assume maker-only fills do not slightly flatter day trading strategies, they completely invert them. A strategy that looks like a steady winner gross can be a guaranteed loser net. The test is simple: the backtest must show a fee total, and the net return must still be positive after it.
Slippage Bites Short Timeframes Harder
On a daily chart, your market order arrives and the daily candle barely moves. On a 15-minute chart, the signal candle is often the volatile one, and the fill lands after the move. Breakout day trading, in particular, buys exactly when the market is moving fastest.
A day trading backtest should assume realistic slippage on every fill, especially for momentum and breakout entries. If the platform's default is zero slippage and instant fills at signal price, the backtest is testing a market that does not exist.
What to Check in a Short-Timeframe Backtest
Check 1: The Trade Count Is Real
Day trading strategies produce enough trades for statistics, but only if the backtest actually logged them. Verify the trade count matches the signal count you expected. A strategy that should fire weekly showing four trades a year has a definition problem, usually an entry condition that almost never triggers.
Check 2: The Window Covers Different Market Hours and Days
Crypto trades 24/7, and sessions behave differently. A strategy validated on two months of data has seen a fraction of the market's behavior. Use a window that includes both trending and ranging weeks, and beware of validation that accidentally covers only one regime.
Check 3: The Costs Match Your Actual Exchange
Your real costs include the exchange fee schedule, not a round number chosen for convenience. A credible short-timeframe test models the taker fee you will actually pay, because at hundreds of trades a year, a few basis points of difference is the entire edge.
Check 4: Look-Ahead Is Impossible
Short timeframes make look-ahead bias seductive because the data is dense. Signals must compute from completed bars only: an entry on a 15-minute close can only use information available at that close, never the bar that follows it. Channel values and indicator outputs must use previous values, or the backtest quietly trades on the future.
Check 5: Drawdown Is Measured in Days, Not Months
Day trading drawdowns compound fast. A 10% drawdown in a week is a different animal from a 10% drawdown over a quarter, because the day trader must keep executing daily while down. Check max drawdown and how long recoveries took, and compare that to how you actually behave after losses.
A Plain-English Validation Example
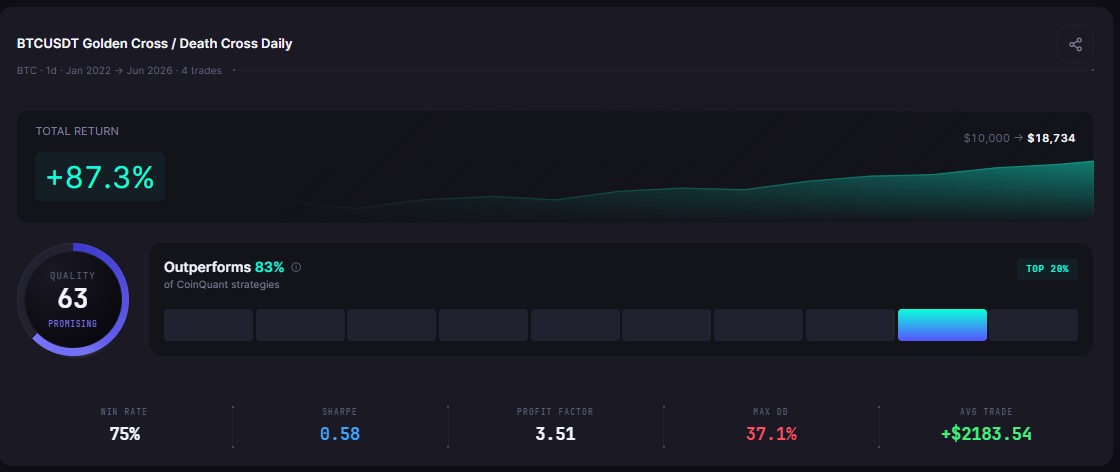
Suppose your setup is: buy when the 15-minute RSI(14) crosses below 30 during an uptrend, sell when it crosses above 50. The validated version of that idea is a complete rule set: asset, timeframe, trend filter, entry, exit, position size, and a fee model. Run over a multi-month window, the backtest reports total trades, win rate, profit factor, max drawdown, and a fee total. If the net profit factor is below roughly 1.5 after modeled costs, the setup is not tradable as defined, no matter how many times it "worked" on your screen.
That is the power of short-timeframe validation: you get the verdict in weeks, not years, and the verdict is about the rules, not about you.
Common Mistakes to Avoid
Validating on a fee-free backtest. For day trading, this is not a simplification, it is a different and imaginary market
Judging by win rate. A day trading strategy can win 60% of trades and lose money if losses run larger than wins
Trusting two months of data. Short timeframes generate many bars, but the window must still span different market conditions
Using instant-fill assumptions for breakout entries. The most volatile fills are exactly where day traders enter
Testing a definition you do not trade. If the backtest uses 100% equity per trade and you trade 5%, you validated someone else's strategy
The Practical Lesson
Day trading needs backtesting more than any other style because frequency multiplies both edge and cost
Fees and slippage are the difference between a day trading strategy and an imaginary one, and they must be modeled per trade
Short timeframes deliver statistically meaningful trade counts fast, which makes honest validation a genuine competitive advantage
Run short-timeframe tests on real exchange data with modeled costs before risking a single live trade
The trader who validates a 15-minute setup for a month learns more than the trader who trades it for a year. Short-term markets punish guesses quickly, which means they reward evidence quickly too. Backtest the setup, read the net numbers, and let the trade count tell you whether the edge is real.
Validate your day trading setup on real intraday data with modeled fees before going live. Test it on CoinQuant
Disclaimer:
Key Takeaway
